How Can You Improve Your Credit Score Before Applying for a Loan?
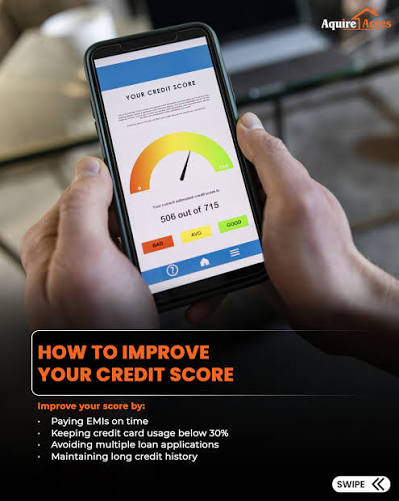
When you plan to apply for a personal loan in Canada, your credit score can play an important role in the lending process. Lenders may review your credit history and score to assess how you have managed credit in the past and determine the terms that may be available to you.
The good news is that there are practical steps you can take to improve your credit profile before submitting a loan application. While improving your credit score usually takes time, responsible financial habits can strengthen your credit history and potentially improve your access to credit.
In this guide, we explain how to improve your credit score before applying for a loan in Canada.
What Is a Credit Score?
A credit score is a three-digit number calculated from information contained in your credit report. In Canada, credit scores generally range from 300 to 900.
Your credit report can include information about your credit cards, loans, lines of credit, payment history, outstanding debts, collection accounts and credit inquiries. Lenders may use your credit report and score when deciding whether to approve a loan and what interest rate or other terms to offer.
A higher credit score may make it easier to access credit and may help you qualify for more favourable borrowing conditions, although approval and loan terms depend on the lender’s criteria and your overall financial situation.
1. Check Your Credit Report Before Applying
One of the first things you should do before applying for a loan is review your credit report.
Checking your own credit report does not hurt your credit score. Reviewing your report allows you to identify inaccurate personal information, incorrect payment records, unfamiliar accounts or other issues that could affect your credit profile.
Canada has two main credit bureaus: Equifax and TransUnion. It can be useful to review information from both because the information appearing on each report may not always be identical.
What should you check?
Look for:
- Incorrect personal information
- Accounts you do not recognize
- Incorrect loan or credit card balances
- Payments incorrectly reported as late
- Accounts that should have been removed
- Unexpected credit inquiries
- Collection accounts that you believe are inaccurate
If you find an error, you have the right to dispute incorrect information with the credit bureau. Credit bureaus must correct errors for free when an investigation confirms that the information is inaccurate.
2. Always Pay Your Bills on Time
Your payment history is one of the most important factors affecting your credit score.
Late or missed payments can negatively affect your credit history, while consistently making payments on time demonstrates responsible credit management.
Before applying for a loan, make sure you have a system that helps you avoid missed payments.
You can:
- Set up automatic payments
- Use payment reminders
- Monitor your bank account before scheduled withdrawals
- Pay at least the minimum amount required if you cannot pay the full balance
- Contact your lender promptly if you expect difficulty making a payment
If you already have several credit accounts, organizing their payment dates can make managing your monthly obligations easier.
Why does this matter?
A lender may view a consistent history of on-time payments as evidence that you manage borrowed money responsibly.
3. Reduce Your Credit Utilization
Another important factor is your credit utilization rate.
Credit utilization measures how much of your available revolving credit you are using. For example, if your credit card limit is $5,000 and your balance is $1,500, your utilization is 30%.
The Financial Consumer Agency of Canada recommends aiming to use less than 30% of your total available credit. It also notes that keeping utilization low can be helpful even when you pay your balance in full each month.
Example
Suppose you have:
- Credit limit: $10,000
- Current balances: $4,000
- Utilization: 40%
Reducing your balances to $2,000 would bring your utilization down to 20%.
A lower utilization rate can show that you are not relying too heavily on available revolving credit.
Practical ways to reduce utilization
Consider:
- Paying down credit card balances
- Avoiding unnecessary purchases on credit
- Keeping balances below your credit limits
- Paying balances before they become difficult to manage
- Avoiding maxing out credit cards
Do not take on new debt simply to improve your credit score. The objective is to manage the credit you already have responsibly.
4. Avoid Applying for Several Loans at the Same Time
When a lender checks your credit report as part of a credit application, this may create a hard inquiry on your credit report.
Several credit applications made within a short period can affect your credit score and may signal to lenders that you are actively seeking significant amounts of credit.
Before applying for a loan, therefore, avoid submitting unnecessary applications to multiple lenders.
Instead:
- Determine how much you actually need.
- Review your budget.
- Research potential lenders.
- Understand their eligibility requirements.
- Apply when you are ready.
There is an important distinction between checking your own credit report and a lender performing a hard credit inquiry. Requesting your own credit report does not affect your credit score.
5. Keep Older Credit Accounts Open When Appropriate
The length of your credit history can also contribute to your credit profile.
Closing an older credit account may reduce the average age of your accounts and reduce your available credit. In some circumstances, keeping an older account open can therefore be beneficial.
However, keeping an account open is not automatically the right choice for everyone.
Consider factors such as:
- Annual fees
- Whether you can manage the account responsibly
- Whether the account is useful
- Your overall debt situation
You should not keep an expensive credit product solely because you are trying to improve your credit score.
6. Pay Down Existing Debt
Before applying for another loan, look at your existing debt.
Lenders may consider your current obligations when assessing a new loan application. Reducing existing balances can help improve your overall financial position and may make it easier to manage an additional monthly payment.
Start by making a list of:
- Credit card balances
- Personal loans
- Lines of credit
- Car loans
- Other monthly debt obligations
Then review your monthly income and expenses to determine how much you can realistically dedicate to debt repayment. The Financial Consumer Agency of Canada recommends reviewing your budget before borrowing and considering whether you can comfortably manage the new payment.
7. Avoid Taking on Unnecessary New Credit
Opening several new credit accounts shortly before applying for a major loan may not be helpful.
New applications can generate credit inquiries, while newly opened accounts can affect aspects of your credit history such as the average age of your accounts.
If you are preparing for an important loan application, focus on managing your existing credit rather than opening several new accounts.
8. Build a Consistent Credit History
Improving a credit score is not usually something that happens overnight.
Credit bureaus receive information from lenders and update credit reports regularly. Your score can change over time as your credit behaviour changes.
The most sustainable approach is to establish consistent financial habits:
- Pay bills on time
- Keep credit utilization under control
- Avoid unnecessary applications
- Manage existing debt
- Monitor your credit report
- Correct inaccurate information
A strong credit profile is generally built through consistency rather than a quick fix.
9. Be Careful With Companies Promising to “Repair” Your Credit Quickly
Be cautious if a company promises to dramatically improve your credit score in a very short period or guarantees loan approval because of a special credit-repair program.
The Financial Consumer Agency of Canada warns that improving a credit score takes time and that some companies may promote high-interest loans as a way to “repair” credit. Such products can leave consumers with additional debt without necessarily improving their credit score.
Before paying for credit-repair services, understand exactly what the company is offering and what it will cost.
10. Create a Budget Before Applying for a Loan
Your credit score is only one part of your financial situation.
Before applying, calculate:
- Your monthly income
- Your essential expenses
- Your existing debt payments
- The amount you want to borrow
- The expected monthly loan payment
- The total cost of borrowing
A loan payment should fit comfortably within your budget.
The Financial Consumer Agency of Canada recommends considering how much you need to borrow, what you can afford to repay each month, whether the expense can wait, and what could happen if your financial situation changes.
How Long Does It Take to Improve Your Credit Score?
There is no universal timeframe for improving a credit score.
Your score is based on information in your credit report, and changes may take time to appear as lenders report updated information to credit bureaus.
For example, consistently paying bills on time and reducing credit utilization can help create a stronger credit profile over time. However, negative information does not necessarily disappear immediately after you change your financial habits.
The key is consistency.
Can You Get a Loan With a Low Credit Score?
Yes, having a low credit score does not necessarily mean that you cannot obtain a loan.
However, your credit history can influence the types of credit available to you and the terms a lender may offer. Other factors can also be considered, such as income, existing debts, employment or financial stability, depending on the lender and loan product.
If your credit score is currently low, focus on improving your overall financial situation rather than submitting numerous applications.
A Simple Pre-Loan Credit Checklist
Before submitting a loan application, consider completing this checklist:
☐ Check your credit reports
☐ Look for errors or unfamiliar accounts
☐ Dispute inaccurate information
☐ Make all payments on time
☐ Reduce high credit card balances
☐ Keep your credit utilization low
☐ Avoid unnecessary credit applications
☐ Review your existing debts
☐ Create a realistic monthly budget
☐ Determine how much you actually need to borrow
☐ Compare the total cost of different loan options
☐ Make sure the expected payment fits your budget
How CREDIT EXPRESS CANADA Can Help
At CREDIT EXPRESS CANADA, we understand that every borrower’s financial situation is different.
Before applying for financing, taking time to understand your credit profile, income, existing obligations and repayment capacity can help you approach the borrowing process more responsibly.
Whether you are considering a personal loan or another financing solution, make sure you understand the applicable interest rate, fees, repayment schedule and total cost before accepting an offer.
Important: Improving your credit score does not guarantee loan approval. Each application remains subject to the lender’s eligibility criteria, credit assessment and applicable requirements.
Frequently Asked Questions
What is the fastest way to improve my credit score?
There is no guaranteed overnight solution. Practical steps include paying bills on time, reducing credit utilization, avoiding unnecessary credit applications and correcting inaccurate information on your credit report.
Does checking my own credit report lower my score?
No. Checking your own credit report does not affect your credit score.
Should I pay off my credit card before applying for a loan?
Reducing credit card balances can lower your credit utilization, which may be beneficial for your credit profile. However, you should also maintain enough cash to cover your essential expenses and existing obligations.
How much credit utilization should I have?
The Financial Consumer Agency of Canada recommends aiming to use less than 30% of your available credit.
Can closing a credit card hurt my credit score?
It can, depending on your situation. Closing an older account may reduce the length of your credit history and your available credit.
How many times can I apply for a loan?
There is no universal number that applies to every borrower. However, multiple credit applications in a short period can create several hard inquiries and may affect your credit score. It is generally better to apply only when you genuinely need credit.
Can I improve my credit score if I already have a poor credit history?
Yes. Improving credit is generally a process of establishing consistent positive financial habits. Paying obligations on time, managing balances responsibly and avoiding unnecessary new debt can help strengthen your credit profile over time.
Final Thoughts
Improving your credit score before applying for a loan is mainly about demonstrating responsible financial behaviour.
Start by checking your credit reports, correcting errors, paying your bills on time and reducing high credit utilization. At the same time, review your budget and existing debts so that you know what you can realistically afford.
A stronger credit profile may help you access more borrowing options or better terms, but your credit score is only one part of a loan application. Lenders may consider your broader financial circumstances when evaluating an application.
If you are considering a loan in Canada, take the time to understand the costs and repayment obligations before making a decision.
Bonjour, ceci est un commentaire.
Pour débuter avec la modération, la modification et la suppression de commentaires, veuillez visiter l’écran des Commentaires dans le Tableau de bord.
Les avatars des personnes qui commentent arrivent depuis Gravatar.